


Supplementary pensions are receiving increasing attention from policymakers and society alike. The government's ambition to ensure that, by 2035, every employee benefits from a supplementary pension contribution of at least 3% of their salary is encouraging many companies to review their pension plan or consider introducing one.
Introducing a group insurance plan is a long-term decision. Your employees' pension capital is often built up over several decades. But which financing solution best matches your objectives and your company?
Many employers choose security. As an employer, you are responsible for the statutory minimum return (currently 2.50%) when an employee retires or leaves the company. If the return generated by the pension provider is insufficient, you must make up the difference. That is why stability and predictability are just as important as potential returns.
💡 This is precisely where one of the key strengths of Branch 21 lies.
Branch 21 is subject to far less pronounced fluctuations in value than solutions that are more closely linked to financial markets. Over the past twenty years, volatility has been just 1.14%, giving employers greater predictability when funding their statutory minimum return obligation.
Branch 21 remains by far the most widely used solution in the Belgian group insurance market
According to Assuralia's latest figures for the fourth quarter of 2025, more than 90% of reserves in the group insurance market are invested in Branch 21. In addition, almost 90% of new premiums continue to be invested in Branch 21.
These figures confirm that many employers prefer solutions that allow them to offer their employees an attractive supplementary pension while limiting their own exposure to financial risk.
Premiums paid into a Branch 21 group insurance plan are invested with a strong focus on stability. Employees benefit from a guaranteed interest rate, which may be supplemented by discretionary profit-sharing when results allow. In this way, we combine security with the potential for additional returns. At AG, the total net return on premiums paid in 2025 amounted to 2.50% last year.
Stability and long-term returns
Employers continue to choose Branch 21 on a large scale not only because of the guarantees it provides, but also because of its long-term performance.
A focus on security does not mean that returns take a back seat. On the contrary, Branch 21 has built a strong long-term track record. For the Branch 21 contracts with a guarantee on reserves, the average annual gross return since 2000 has been 3.54%. This is higher than the average inflation rate of 2.39% over the same period. Branch 21 has therefore not only demonstrated its stability but has also helped limit the impact of inflation on pension savings over the long term.*
AG increases the guaranteed interest rate from 1 January 2027
As Belgium's market leader, AG plays a leading role in the supplementary pensions market.
This year is no exception, with an increase in the guaranteed interest rate on new premiums to 2.75% for the Branch 21 group insurance plans with a guarantee on reserves. Depending on financial market developments and AG's financial results, discretionary profit-sharing may be awarded each year in addition to this guaranteed rate. This provides you, as an employer, with maximum certainty.
We invest Branch 21 assets primarily in fixed-income investments, such as high-quality government bonds. At the same time, we continuously take account of the pension capital we will need to pay out in the future, enabling us to meet our long-term commitments at all times.
For you as an employer, this means greater peace of mind. Your pension plan is based on stable long-term growth and is not entirely dependent on fluctuations in financial markets. Your employees also appreciate knowing that their supplementary pension is being built within a stable framework. Financial security remains an important expectation for their future.
* For contracts with a guarantee on reserves. Past returns do not guarantee future returns.
Pension reserves that also support Belgium's future
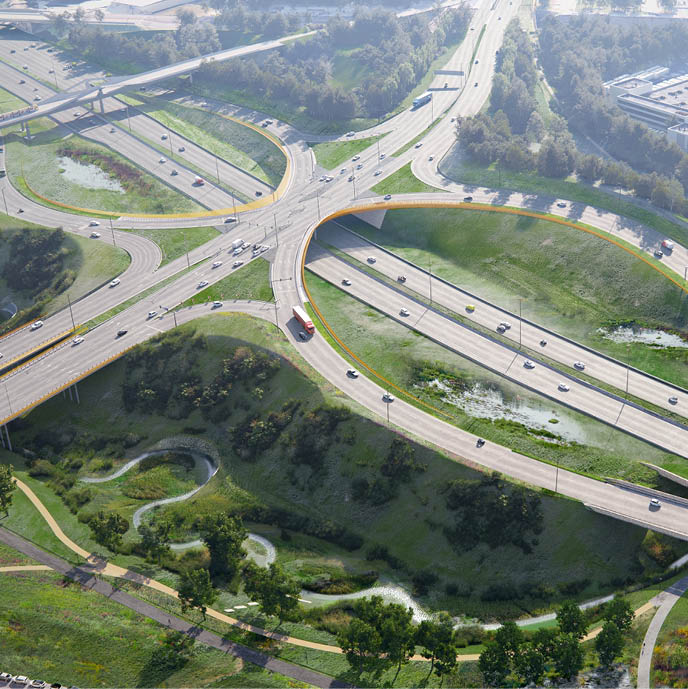
Branch 21 does more than help build your employees' supplementary pensions. The reserves are also invested in the Belgian economy. Examples include schools, railways, social housing, water treatment facilities, courthouses and mobility projects.
Investments in wind farms, solar energy, green mobility and environmentally friendly buildings also contribute to a more sustainable Belgian society..
This local focus sets Branch 21 apart from many internationally diversified investment funds. Your employees' pension capital is therefore not only being built for the future but is already being used today for projects that help Belgium move forward economically and socially.
Different companies have different needs
Although Branch 21 remains a logical choice for many employers, the most appropriate financing solution always depends on your company's specific objectives.
Some employers are willing to take on more risk in exchange for higher potential returns over the long term. Others prefer a balance between security and growth opportunities. That is why Branch 23 solutions and hybrid approaches combining features of both are also available.
The right choice depends on several factors: your budget, your employees' expectations, your approach to risk and the extent to which you want to be involved in monitoring the pension plan. The key is not to start with a product, but with your objectives as an employer.
La communication fait aussi la différence
A strong pension plan only creates real value when employees understand the benefits they receive. Yet many employees have only a limited understanding of their accrued pension rights and other insured benefits. Clear communication and user-friendly digital tools can make a significant difference.
Through the MyAG Employee Benefits app, plan participants can consult their accrued reserves, run simulations and access documents. The app also provides an overview of other insurance cover and benefits, including hospitalisation, disability and death cover.
The better employees understand the benefits you offer, the more they will appreciate their overall remuneration package!
Ready for the future?
Tomorrow's group insurance plan requires a balance between returns, stability and societal impact. Branch 21 brings these three elements together: an attractive long-term track record, limited exposure to market volatility and investments that support the Belgian economy.
By taking a closer look at your pension plan today, you can make choices that will have a positive impact for years to come, for both your employees and your company. Investing in your employees' future remains one of the most valuable investments you can make as an employer.
Questions?
Would you like to know more about our pension solutions? Please contact your usual representative. We will be happy to help.